How tax changes, EVs, and interest rates are shaping Canada’s dealership buy-sell market

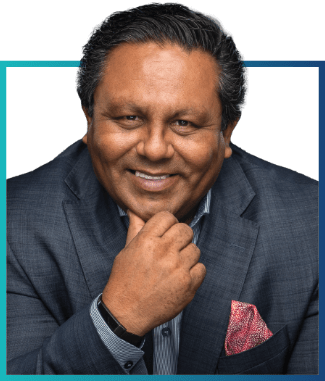
Farid Ahmad


The market for dealership mergers and acquisitions in the Canadian market has picked up strength as the year progressed. Yet it still remains vulnerable to volatile external factors, ranging from changes to the capital gains tax to rising vehicle inventories to falling interest rates. Farid Ahmad, the founder and Chief Executive Officer of DSMA, explains how these forces and others could impact the buy-sell market for the remainder of 2024–and into 2025.

Q: How did the market for dealership acquisitions play out this year, compared to your expectations? Are there any lessons from 2024 that can be applied to expectations for 2025?

Farid Ahmad: Our expectations for the dealership acquisition market in 2024 have largely been met, with DSMA on track to achieve its sales objectives for the year. While the first quarter saw fewer transactions than initially forecasted, the market gained momentum as the year progressed and our fourth quarter will be strong, with an uptick in closings.

A key insight has been the volume of discussions we are having with our friends in various manufacturers’ dealer-development departments, many of whom report record levels of dealership transactions this year. This surge includes not only our own deals, but also a notable number of private transactions.

Looking ahead to 2025, a critical lesson is to remain adaptable to fluctuations within the year, as the market can experience rapid shifts in activity.

Q: How have the changes to the federal government’s tax system–most notably the changes in the capital gains tax–affected the pace of dealership acquisitions and how is that likely to play out in 2025?

Ahmad: The recent changes to the federal capital gains tax have certainly influenced the timing of dealership acquisitions. With minimal lead time from the government, many business owners expedited their plans to sell, which resulted in an influx of early transactions. This led to a surge in consultations with accounting firms as clients sought to understand the implications of the new tax regime.

Our strong partnerships with major accounting firms across Canada allowed us to collaborate closely and support our clients in navigating these changes. Unfortunately, some business owners were unable to complete their transactions before the higher capital gains tax took effect, which was a missed opportunity.

As we look toward 2025, we anticipate that tax changes will continue to impact the timing and volume of acquisitions.

Q: AutoCanada Inc. recently announced that it’s exploring the sale of its dealerships in the United States. Does this suggest a trend that could affect dealership acquisitions in Canada?

Ahmad: The recent announcement by AutoCanada regarding the potential sale of its U.S. dealerships is not indicative of a broader trend that would significantly impact the dealership acquisition climate in Canada. AutoCanada’s decision seems to stem from specific challenges they faced in the U.S. market, including initial overvaluation of acquisitions and operational differences between the Canadian and U.S. markets. It’s crucial for Canadian dealers to recognize these distinctions when considering cross-border acquisitions.

Q: Is the auto industry’s unexpectedly sluggish transition to electric vehicles (EVs) affecting dealership acquisitions?

Ahmad: In our experience, the slower-than-expected transition to EVs has not significantly impacted dealership acquisitions. We have yet to encounter a buyer who has explicitly asked us to avoid presenting specific brands due to their EV strategies.

While the industry’s shift toward EVs certainly is a topic of interest, it has not deterred potential buyers from exploring opportunities with brands at various stages of their EV transitions. The focus remains on the overall performance and potential of a dealership, rather than its alignment with a particular EV strategy.

“As we look toward 2025, we anticipate that tax changes will continue to impact the timing and volume of acquisitions.”


Q: Is Honda Canada’s plan to reduce dealer profit margins an anomaly or an action that other automakers are likely to impose–and how would that affect dealership buy-sell activity?

Ahmad: Honda Canada’s decision to reduce dealer profit margins has had a notable impact on the valuation of its dealerships. Just a few years ago, there was a high demand for Honda stores, but that landscape has shifted significantly. When a manufacturer reduces dealer profit margins to the extent that it materially affects a dealership’s profitability, it inevitably leads to a decline in the value of that franchise.

If other automakers were to implement similar measures, it would likely have a broader impact on dealership buy-sell activity, with reduced profitability leading to lower valuations and potentially less interest from buyers. It’s a reminder that manufacturers’ policies directly influence the stability of dealer networks and the attractiveness of their franchises in the acquisition market.

Q: Clearly, some auto brands are more attractive for acquisition than others. Which brands are likely to be the most coveted by prospective dealership buyers?

Ahmad: Certain auto brands consistently stand out as more attractive acquisitions, due to their strong market performance, brand loyalty and profitability. Currently, the brands most coveted by prospective buyers are Audi, Hyundai, Kia, Subaru, Lexus, Mercedes-Benz, Porsche and Toyota.

These brands are often sought after because they offer a combination of robust sales volume, high customer retention and a diverse product lineup that appeals to a wide range of consumers. Their strong positioning in the market makes them prime targets for acquisition, as buyers are looking to capitalize on these brands’ growth potential and established reputations.

Q: Falling interest rates and rising inventories have been good signs for 2024. Any other factors that could affect dealership acquisition activity going forward?

Ahmad: While the prospects of falling interest rates and rising inventories have been positive indicators for dealership acquisition activity in 2024, other factors could also play a significant role as we move into 2025. One such factor is the upcoming U.S. elections, which could influence U.S. automakers and subsequently impact the Canadian dealer network, depending on the policy changes that may follow.

Additionally, fluctuations in used-car inventories and values remain a critical area to monitor. Changes in supply and demand for pre-owned vehicles can directly affect dealership profitability and acquisition strategies, as they play a pivotal role in overall dealership performance.

Q: In the next year, will buying a dealership in Canada get easier, harder or remain about the same?

Ahmad: We anticipate that buying a dealership in Canada next year will remain much the same as in 2024. However, the process of closing deals has become increasingly complex and time-consuming, with greater scrutiny from banks, buyers, lawyers and manufacturers. Currently, it takes an additional 32 days on average from the execution of a letter of intent (to final closing, compared to previous years.

We hope to see a return to more streamlined closing timelines in 2025, as the current extended process poses challenges for both buyers and sellers. Nonetheless, we expect the overall environment for dealership acquisitions to remain stable, with continued diligence required at every step of the process.


For additional articles and panels visit Automotive News Canada | The latest on the Canadian auto industry, from retail to assembly, the supply chain and more. (autonews.com)
Share This

Psst... we have cookies.

By clicking “Accept Cookies”, you agree to the storing of cookies on your device to enhance site navigation, analyze site usage, and assist in our marketing efforts.